
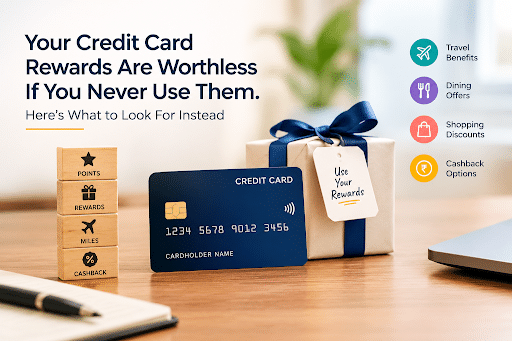
Let’s be honest about something. Most of us have a rewards balance sitting somewhere that we haven’t touched in months, possibly years. Points from a travel rewards credit card that require a portal login, a specific airline partner, a redemption window, and enough patience to actually get through the process. By the time you do, the points are worth less than you calculated, or the flight you wanted isn’t available for redemption at all.
This isn’t a niche problem. It is the standard experience with most credit cards in India, and for working professionals who travel on weekends and want their card to actually fund that lifestyle, the gap between what was promised and what gets delivered is significant.
Why Most Reward Systems Disappoint the People Who Use Them Most?
The older generation of travel rewards credit cards was built around a specific kind of traveller. Someone who flies frequently enough to understand airline mile transfer ratios, who has the time to optimise redemptions, and who carries a card with a ₹3,000-5,000 annual fee that needs to be justified before it delivers a rupee in value.
For the working millennial flying Bengaluru to Mumbai on a Friday and coming back Sunday, that system is largely decorative. The points accumulate, the thresholds stay just out of reach, and the annual fee gets charged regardless.
What this kind of traveller actually needs is simpler: a co-branded travel credit card where spending on regular life visibly builds toward the next trip, and where the redemption works without a tutorial.
The Scapia Federal Credit Card and What It Does Differently
The Scapia credit card, issued in partnership with Federal Bank, BOBCARD and now Axis Bank, is built around a loop that is considerably easier to understand and use.
Every eligible spend on the Visa card earns 10% back as Scapia Coins. Book travel through the Scapia app and that rate goes to 20%. UPI payments above ₹500 through Scapia Pay on the complimentary RuPay card earn 5% back. Five coins equal ₹1 in travel value, no minimum redemption, no cap on earnings, no expiry pressure within 36 months.
The coins redeem directly at checkout inside the Scapia app against flights, trains, buses, domestic and international hotel stays, visa applications across 40+ countries, and even curated travel experiences. No portal, no partner transfer, no ratio calculation required.
What the Axis Bank Partnership Changes?
In September 2026, Axis Bank joined as the third issuing partner for the Scapia card alongside Federal Bank and BOBCARD. The Axis variant runs on Mastercard and RuPay rather than Visa and RuPay, but the core proposition stays identical: zero annual fee, zero forex markup, same coin earning rates, same travel ecosystem.
The practical implication for applicants is meaningful. If you were previously rejected by Federal Bank due to their one-card policy, the Axis Bank route is now a legitimate alternative with its own approval criteria. More distribution, same card, more people who can access it.
Zero Forex on a Zero Fee Card
As a zero forex fee credit card, Scapia applies no foreign currency markup on international transactions. What you spend abroad in any currency is what appears on your statement in INR, calculated at the Visa or Mastercard network rate with nothing added on top. For a weekend trip to Bangkok or a longer Europe itinerary, the difference versus a standard card charging 3.5% plus GST adds up to a meaningful number on any spend above ₹50,000.
This also applies to international subscriptions billed in foreign currency, so the benefit is working even on months with no travel at all.
What to Actually Look For?
When evaluating a credit card with travel benefits, three things determine whether the rewards are usable or just theoretical. First, can you redeem without navigating a partner ecosystem? Second, does the card earn on how you actually spend, not just on categories that suit the bank? Third, does it cost you anything before it gives you anything back?
Scapia credit card eligibility is open to both salaried and self-employed applicants, with a fully digital application and video KYC through the app. No branch visits, no paperwork.
The rewards on most cards aren’t bad because of the rate. They’re bad because the system between earning and using is designed to reduce how much you actually extract. The fix is not finding a higher earn rate on the same model. It’s using a card where the loop is shorter and the redemption is something you’ll actually do.